Surcharging vs Cash Discounting: The Zero-Cost Processing Trap
Analyze the real costs of surcharging vs cash discounting. Learn how 'zero-cost' processing impacts margins, compliance, and your customer experience.
The Direct Answer: Surcharging vs. Cash Discounting
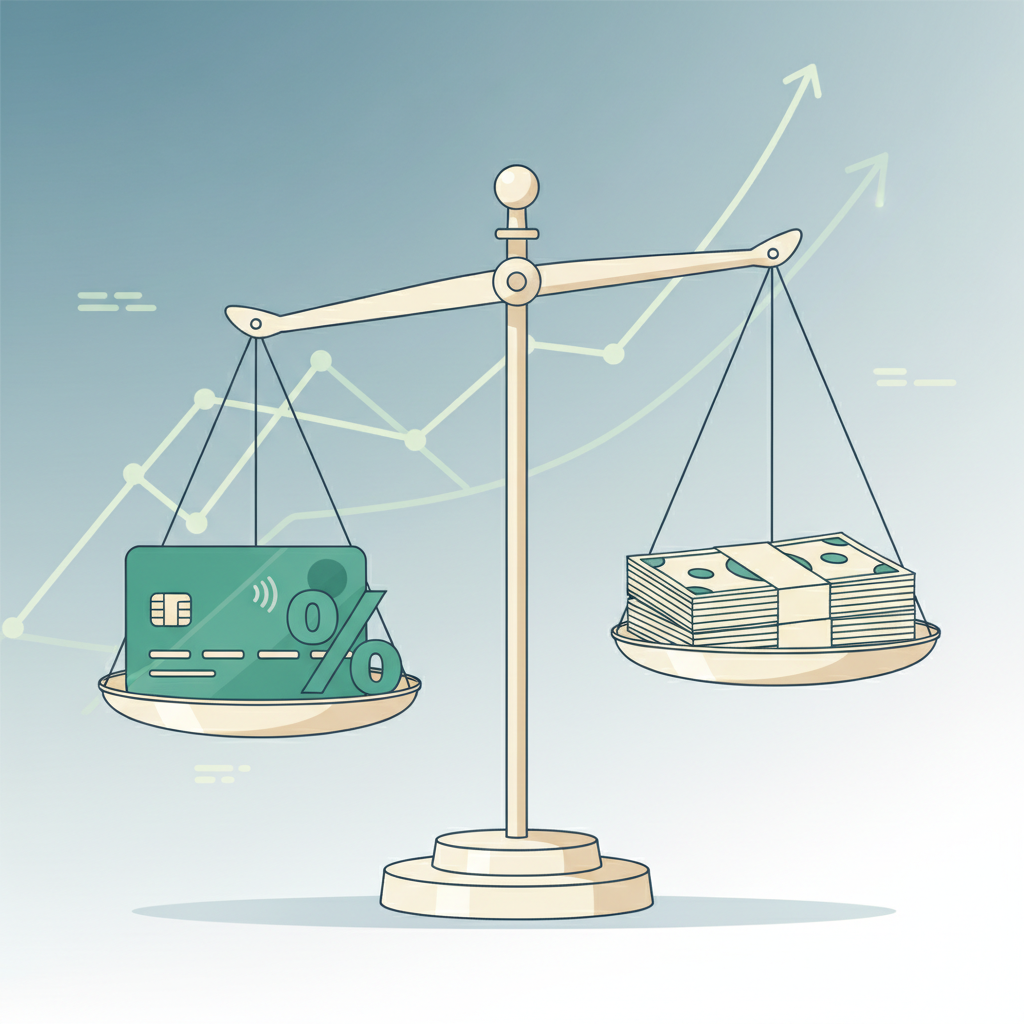
Surcharging is the practice of adding a specific percentage fee to a transaction when a customer pays with a credit card, whereas cash discounting involves offering a lower price than the listed 'standard' price for customers who pay with cash or check. While both models aim to shift the burden of credit card processing fees from the merchant to the consumer, they are governed by vastly different legal frameworks, card brand rules, and psychological impacts on customer loyalty.
In the payments industry, the siren song of "zero-cost processing" is loud. For a business owner tired of seeing thousands of dollars in interchange fees vanish from their bottom line every month, the promise of a 0% processing bill is almost irresistible. However, at OrbitBNK, we see the back-end data: many "zero-cost" programs are actually high-margin traps for the processor that can lead to compliance headaches and customer attrition for the merchant.
The Financial Engineering of "Zero-Cost" Programs
There is no such thing as truly free payment processing. Someone, somewhere, is paying the interchange fee to the issuing bank, the assessment fee to the card brand (Visa/Mastercard), and the markup to the processor. In a standard model, the merchant pays these. In a "zero-cost" model, the customer pays them.
When a processor sells you on a 4% flat-fee surcharge or cash discount program, they aren't doing it to be charitable. If your actual cost of processing (the "effective rate") is 2.2%, and you charge your customers 4%, that 1.8% spread is pure profit for the processing company—not you. You are essentially acting as a tax collector for your merchant service provider, often while risking your brand reputation.
Surcharging: The Regulatory Tightrope
Surcharging is the most transparent, but also the most regulated, way to pass on fees. If you choose this route, you must follow strict guidelines set by the card networks and state governments.
- Credit Cards Only: You cannot surcharge debit cards or prepaid cards, even if they are run as "credit" (no PIN). This is a common point of failure where merchants unknowingly violate the Durenberger Amendment and the Durbin Amendment.
- The 3% Cap: As of 2023, Visa and Mastercard have capped surcharges at 3% (previously 4%). If your processor is setting you up at 3.5% or 4%, you are out of compliance from day one.
- Registration and Signage: You must notify the card brands 30 days in advance and display clear signage at the point of entry and the point of sale.
- State Restrictions: While many state bans have been overturned on First Amendment grounds, states like Connecticut and Massachusetts still have strict prohibitions or complexities regarding surcharging.
Cash Discounting: The Legitimate Alternative?
Cash discounting is often marketed as the "legal workaround" to surcharging because it applies to all forms of payment. However, most programs marketed as "Cash Discounting" are actually "Non-Cash Adjustments," which are a legal gray area.
True cash discounting requires you to have a posted price (e.g., on a menu or a price tag) that is the actual price, and then provide a discount for cash. If your posted price is the cash price, and you add a fee at the register for cards, that is a surcharge—regardless of what your processor's marketing materials call it.
To be compliant with a true cash discount program, your "regular price" must be the credit price, and the discount must be a reduction from that price. Most "zero-cost" software simply adds a line item to the receipt, which technically qualifies as a surcharge, triggering all the regulatory requirements mentioned above.
Dual Pricing: The Emerging Industry Standard
Because of the confusion between surcharging and cash discounting, many high-end merchants are moving toward "Dual Pricing." This is the most transparent model for the consumer. You list two prices for every item: a "Card Price" and a "Cash Price."
This model is generally favored by regulators because it removes the "hidden fee" element at the end of the transaction. The customer knows exactly what they will pay before they reach the terminal. From a financial analysis perspective, dual pricing often sees less customer pushback than a surprise surcharge added after the total is rung up.
The Real Impact on Customer Lifetime Value (CLV)
As a merchant, you must weigh the short-term gain of saving 3% on processing against the long-term risk of losing a customer.
Imagine a restaurant where the average ticket is $100. By surcharging 3%, the owner saves $3.00. However, if that $3 fee irritates a loyal customer who eats there once a month, and they decide to stop coming, the owner loses $1,200 in annual revenue to save $36 in fees.
Financial analysis of merchant data shows that in highly competitive industries (like retail and dining), surcharging can lead to a 5-10% drop in customer retention. In "must-have" or niche services (like specialized repair or B2B), the impact is much lower. You must understand your price elasticity before flipping the switch on a zero-cost model.
How to Spot a Bad "Zero-Cost" Deal
If you are evaluating a proposal for a surcharge or cash discount program, look for these red flags:
- The Flat 4%: If the processor proposes a 4% fee, they are likely ignoring the new 3% cap for credit card surcharging or assuming you won't get caught.
- Proprietary Hardware Requirements: Some processors force you to buy specific, overpriced terminals because their "special" software is the only way to handle the math. In reality, most modern POS systems can handle this.
- The "No Statement" Tactic: Some providers stop sending you detailed statements because "your cost is zero." This makes it impossible to see if they are sneaking in monthly service fees, PCI non-compliance fees, or hardware rentals that actually exceed what you were paying before.
- Debit Surcharging: If their system surcharges debit cards, run away. It is a violation of federal law and can lead to massive fines from the card brands.
The OrbitBNK Recommendation: A Data-Driven Approach
Before moving to a zero-cost model, you need a baseline. You cannot manage what you do not measure.
- Calculate your current Effective Rate: Total fees divided by total gross volume. If your effective rate is 2.4% and a processor wants to charge your customers 3.5%, you are giving away 1.1% of your volume to the processor for no reason.
- Analyze your Ticket Size: Surcharging is much more palatable on a $1,000 B2B invoice than on a $4.00 cup of coffee.
- Check your Merchant Category Code (MCC): Certain industries have different rules and customer expectations.
At OrbitBNK, we believe in transparency over gimmicks. While shifting costs to consumers is a valid business strategy in some scenarios, it should be done with a full understanding of the margin distribution and the compliance risks involved.
Wondering if your "Zero-Cost" program is actually costing you a fortune in hidden spreads and lost customers?
Upload your most recent processing statement for a free, no-obligation OrbitBNK Audit. We’ll strip away the marketing jargon to show you exactly what you’re paying, what your customers are paying, and where the processor is hiding their profit.
Frequently asked questions
Is it better to use a surcharge or a cash discount?+
It depends on your business model. Surcharging is more transparent but restricted to credit cards and capped at 3%. Cash discounting covers all payment types but requires you to list higher 'standard' prices, which might discourage some customers. Dual pricing is often the most compliant and customer-friendly middle ground.
Is surcharging legal in all 50 states?+
While most state bans have been challenged, surcharging remains complex in states like New York, Maine, and Connecticut, which have specific requirements for how prices are displayed. Always consult a legal expert or a payment professional before implementing these programs in those states.
Can I surcharge a debit card if I run it as credit?+
No. Federal law (the Durbin Amendment) and card brand rules strictly prohibit surcharging debit cards, regardless of whether the customer signs or uses a PIN. Surcharging a debit card is a major compliance violation.
What is the maximum surcharge amount allowed by Visa and Mastercard?+
As of early 2023, the maximum surcharge allowed by the major card networks is 3.0%. Any processor setting a surcharge higher than this is putting the merchant at risk of fines or account termination from the card brands.
Will a cash discount program hurt my sales?+
Data shows it varies by industry. In price-sensitive retail or dining, a sudden fee can lead to customer friction. However, in B2B or high-ticket service industries, customers are often more accustomed to passing on credit costs and the impact on sales volume is usually minimal.
See your real processing math
Upload your merchant statement for a free, line-by-line OrbitBNK review.
Start The Clearing