Surcharge vs Cash Discount for Merchants: 2026 Savings Guide
Deciding between surcharge vs cash discount for merchants? Our 2026 guide breaks down compliance, costs, and the best way to eliminate processing fees.
The Direct Answer: Which Program Wins in 2026?
In 2026, the choice between a surcharge vs cash discount for merchants comes down to a trade-off between simplicity and coverage. Surcharging typically offers the most direct path to offsetting credit card fees but is strictly prohibited on debit cards and remains legally complex in several states. Conversely, Dual Pricing—the modern, compliant evolution of the Cash Discount—allows merchants to offset costs across nearly all card types by presenting a clear 'Cash' and 'Card' price, making it the more robust savings vehicle for high-volume retail and service businesses.
Navigating the Shift in Processing Costs
As we navigate the 2026 payment landscape, the margin for error in merchant processing has vanished. For years, business owners viewed credit card processing fees as an unavoidable 'cost of doing business.' However, with interchange rates shifting and card brand rules tightening, the conversation has moved from 'how much do I pay?' to 'how do I pass these costs on responsibly?'
Understanding the nuances of 'surcharge vs cash discount for merchants' is no longer just for the cost-conscious; it is a fundamental requirement for maintaining healthy margins. While both programs aim for 'Zero-Cost Processing,' their execution, legal standing, and impact on customer retention vary significantly.
What is Credit Card Surcharging?
Surcharging is the practice of adding a specific fee—typically a percentage—to a transaction when a customer pays with a credit card. This fee is designed to cover the merchant's cost of acceptance.
The Strict Rules of Surcharging in 2026
Surcharging is the most heavily regulated of the two programs. To stay compliant with Visa, Mastercard, and state laws, merchants must adhere to several non-negotiable points:
- No Debit Cards: This is the most common point of failure. You cannot surcharge a debit card, even if it is run as 'credit' (signature-based). In 2026, with the continued rise of contactless debit payments, this means a significant portion of your transactions will still incur fees.
- The 3% Cap: Following the 2023 card brand adjustments, the maximum surcharge is capped at 3% or your actual cost of acceptance, whichever is lower. Attempting to 'profit' from a surcharge is a fast track to a merchant account termination.
- 30-Day Notification: You must notify the card brands (Visa/Mastercard) at least 30 days before you begin surcharging.
- Clear Signage: Merchants must provide clear disclosure at the point of entry and the point of sale, stating the surcharge percentage.
- Line Item Detail: The surcharge amount must appear as a separate line item on the customer’s receipt.
What is Cash Discounting (and Dual Pricing)?
Technically, a 'Cash Discount' is when a merchant posts a price for a product and offers a discount if the customer pays with cash, check, or another non-card method. However, the industry has largely shifted toward Dual Pricing to ensure compliance with the Durbin Amendment and various consumer protection acts.
Why Dual Pricing is the 2026 Standard
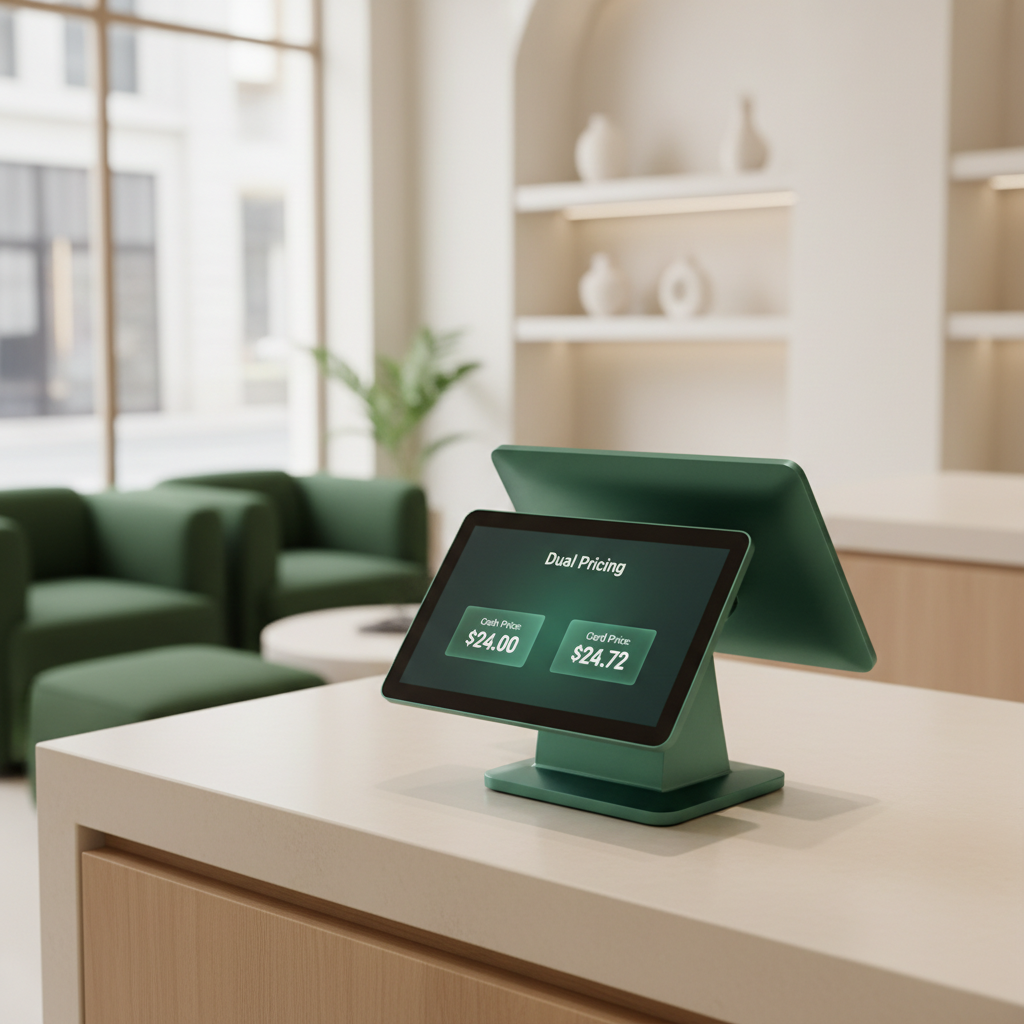
Dual Pricing eliminates the 'hidden' nature of fees by showing the customer two distinct prices for every item: one for cash and one for card. Because the 'Credit Price' is the listed price, and the 'Cash Price' is a reduction, this model is not legally considered a surcharge.
This distinction is vital. Since it is not a surcharge, it is generally legal in all 50 states (including those that historically restricted surcharging like New York and Connecticut) and can effectively be applied to both credit and debit card transactions, provided the pricing is displayed transparently.
Surcharge vs Cash Discount for Merchants: A Financial Comparison
To understand which program saves more, let’s look at a hypothetical merchant, 'Summit Auto Repair,' with $100,000 in monthly volume (60% Credit, 30% Debit, 10% Cash).
Scenario A: Surcharging (3%)
- Credit Volume ($60k): Merchant collects $1,800 in surcharge fees. This offsets most of the credit processing costs.
- Debit Volume ($30k): No surcharge allowed. The merchant pays roughly 1.5% - 2.5% in fees ($450 - $750).
- Net Monthly Cost: ~$600 (plus software fees).
Scenario B: Dual Pricing / Cash Discounting
- Credit Volume ($60k): Customer pays the 'Card Price.' Processing costs are covered by the price delta.
- Debit Volume ($30k): Customer pays the 'Card Price.' Processing costs are covered.
- Net Monthly Cost: ~$0 (plus a small monthly software subscription).
In this 2026 reality, Dual Pricing typically 'saves' the merchant more because it captures the debit card volume that surcharging ignores. For businesses with high debit usage—like coffee shops, gas stations, or fast-casual dining—Dual Pricing is the clear financial winner.
The Compliance Trap: 'Non-Cash Adjustments'
A word of caution for 2026: The industry is cracking down on 'Non-Cash Adjustments' (NCA). This is a legacy practice where merchants simply add a fee to every transaction and call it a 'Cash Discount' on the receipt. Regulators and card brands now view this as 'de facto surcharging.' If you are adding a fee at the register that isn't reflected in the shelf price, and you aren't following surcharge rules, you are at risk of heavy fines.
True Dual Pricing requires your Point of Sale (POS) system to handle two separate price fields. If your current processor is just 'tacking on a fee' and calling it a discount, you are likely out of compliance.
Customer Psychology and Perception
Beyond the math, you must consider the 'friction' each program creates.
- Surcharging can feel like a penalty. Customers see an extra charge added to their total, which can lead to 'sticker shock' at the last second of the transaction.
- Dual Pricing feels like a choice. When a customer sees a $10.00 cash price and a $10.30 card price on a menu or shelf tag, they make the decision before they reach the counter. This transparency has been shown to reduce customer complaints by up to 40% compared to traditional surcharging.
Strategic Recommendations for 2026
As an expert in the field, here is how I advise merchants to choose:
- Choose Surcharging if: You are a B2B company with high average tickets, your customers almost exclusively use corporate credit cards (which have high interchange rates), and you operate in a state where surcharging is culturally normal.
- Choose Dual Pricing if: You are a B2C retail or service business with significant debit card traffic, you operate in multiple states with varying laws, and you want to maximize your savings while maintaining a transparent customer experience.
The Importance of an Independent Audit
Every merchant’s 'Effective Rate' is different. You might think you’re saving money with a flat-rate surcharge program, but hidden 'statement fees,' 'PCI non-compliance fees,' and 'minimum processing fees' can still eat into your bottom line. In 2026, the complexity of interchange (including the myriad of 'Utility' vs. 'Rewards' vs. 'Infinite' card tiers) means that a one-size-fits-all approach rarely works.
At OrbitBNK, we don't just sell processing; we provide payment intelligence. We help you look under the hood of your merchant statement to see exactly where your money is going and whether a Surcharge, Cash Discount, or traditional Interchange-Plus model actually serves your business best.
Stop guessing about your processing costs. Upload your most recent merchant statement today for a free, no-obligation OrbitBNK review. We will show you exactly how much you can save in 2026—without the hidden fees.
Frequently asked questions
What is the main difference between a surcharge and a cash discount?+
A surcharge is an additional fee added to a credit card transaction to cover processing costs, while a cash discount is a reduction in the posted price for customers who pay with cash. In 2026, many merchants use 'Dual Pricing' to show both prices upfront for maximum transparency.
Is it legal to surcharge debit cards in 2026?+
No. Under Visa and Mastercard rules, as well as federal law (Durbin Amendment), you cannot surcharge a debit card, even if it is processed as 'credit.' Surcharging is strictly for credit cards only.
What is the maximum surcharge amount allowed?+
As of 2026, most major card brands cap the surcharge at 3% or your actual cost of acceptance, whichever is lower. It is illegal to profit from a surcharge.
Are cash discount programs legal in all 50 states?+
Yes, true cash discount and dual pricing programs are generally legal in all 50 states because they are considered a discount for cash rather than a penalty for using a card. However, they must be implemented with clear, transparent pricing to avoid being classified as an illegal surcharge in certain states.
Will customers be upset by a surcharge or dual pricing?+
While some friction is possible, studies show that customers are more accepting of 'Dual Pricing' where they see the choice upfront. Transparency is the key to maintaining customer loyalty while offsetting processing costs.
See your real processing math
Upload your merchant statement for a free, line-by-line OrbitBNK review.
Start The Clearing