Interchange-Plus vs Flat-Rate Pricing: Which Actually Saves Merchants Money?
Compare interchange-plus vs flat-rate pricing to discover which model minimizes costs. Learn how to analyze your effective rate and find the best processing deal.
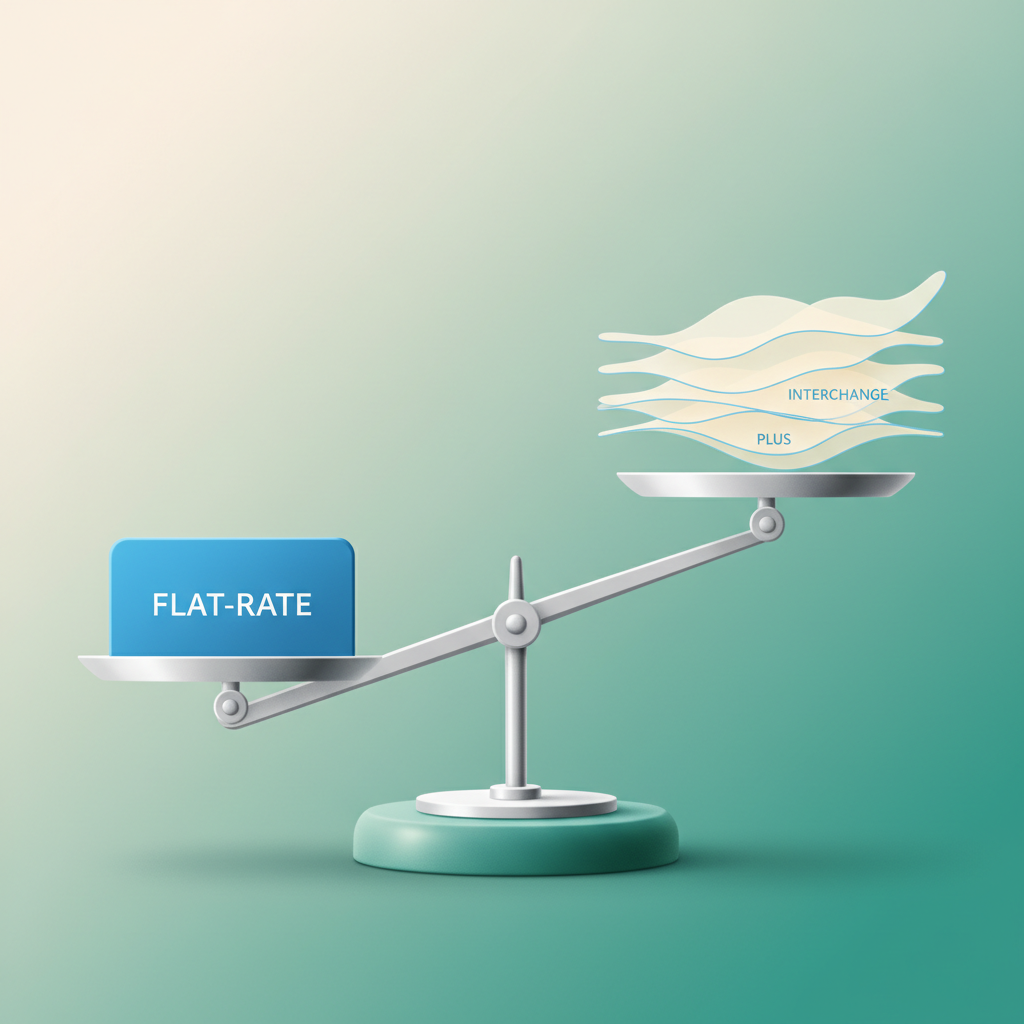
Interchange-plus pricing is the gold standard for established businesses, offering transparent access to wholesale rates that typically save merchants 20% to 40% compared to flat-rate models. While flat-rate pricing offers predictable simplicity for low-volume startups, the high 'convenience markup' becomes a significant financial burden as a business scales, particularly on debit card and high-ticket transactions.
The Great Debate: Simplicity vs. Transparency
In the world of merchant services, the pricing model you choose is often more important than the processor itself. Merchants are frequently forced to choose between two diverging philosophies: the 'all-in' simplicity of flat-rate providers (like Square or Stripe) and the 'wholesale-plus' transparency of interchange-plus providers. To understand which saves you more money, we first have to peel back the layers of how a credit card transaction is actually priced.
Every time a customer swipes a card, three distinct fees are triggered: interchange (paid to the issuing bank), assessments (paid to the card brands like Visa/Mastercard), and the processor's markup. The first two are non-negotiable and identical for every processor. The third—the markup—is where the battle for your bottom line is won or lost.
Understanding Flat-Rate Pricing: The 'Convenience' Trap
Flat-rate pricing is exactly what it sounds like. You pay a single, fixed percentage (and usually a per-transaction cent fee) regardless of the card type used. A common example is 2.9% + $0.30.
The Pros of Flat-Rate
- Predictability: You know exactly what you will pay on every sale, making accounting straightforward.
- No Monthly Fees: Most flat-rate providers eliminate monthly service fees or PCI compliance charges.
- Ease of Entry: These platforms allow for near-instant approval, which is vital for new businesses.
The Cons of Flat-Rate
The fatal flaw of flat-rate pricing is that it is designed to cover the processor's highest possible costs while still leaving them a profit. If the 'wholesale' cost of a debit card transaction is only 0.05% + $0.21, but you are paying a flat 2.9% + $0.30, the processor is pocketing a massive markup. For businesses with high average tickets or a high volume of debit cards, this model is objectively expensive.
Interchange-Plus: The Transparent Wholesale Model
Interchange-plus (also known as 'cost-plus') is the model preferred by sophisticated CFOs and high-volume merchants. In this setup, the processor passes the literal cost of the interchange fee and assessments directly to you, then adds a small, fixed markup (e.g., 0.20% + $0.10).
The Pros of Interchange-Plus
- Total Transparency: Your monthly statement shows exactly what the card brands charged and exactly what the processor earned.
- Lower Costs on Low-Risk Cards: When a customer uses a basic debit card or a non-rewards credit card, you pay the lower wholesale rate, not an inflated flat fee.
- Optimization Opportunities: This model allows for 'Level 2' and 'Level 3' processing, which significantly reduces rates for B2B and government transactions by providing more data at the point of sale.
The Cons of Interchange-Plus
- Statement Complexity: These statements can be several pages long and difficult to read without a payment intelligence tool.
- Variable Monthly Costs: Your 'effective rate' will fluctuate slightly month-to-month based on the mix of cards your customers use.
The 'Smoking Gun': Debit Card Disparities
To see the math of savings in action, let's look at a $100 transaction using a standard regulated debit card.
Under a Flat-Rate model at 2.9% + $0.30, you pay $3.20.
Under an Interchange-Plus model (assuming a markup of 0.20% + $0.10), the cost breakdown looks like this:
- Interchange (Regulated Debit): 0.05% + $0.21 = $0.26
- Assessments: ~0.13% = $0.13
- Processor Markup: 0.20% + $0.10 = $0.30 Total Cost: $0.69
In this scenario, the merchant using interchange-plus saves $2.51 on a single $100 sale. Scale that across thousands of transactions, and the 'simplicity' of flat-rate pricing starts to look like a very expensive tax on your growth.
Deciphering the 'Effective Rate'
The only way to truly compare these two models is by calculating your effective rate. This is the 'real' percentage you pay after all fees, including per-transaction costs and monthly dues. To find it, divide your total processing fees by your total sales volume.
If you process $50,000 and your total fees are $1,500, your effective rate is 3.0%. For a healthy, mid-sized business on an interchange-plus plan, an effective rate should generally hover between 1.8% and 2.4%, depending on industry and card-present status. If your effective rate is consistently above 2.8%, you are likely overpaying—either through a flat-rate model or a poorly negotiated interchange-plus deal.
When Does the Switch Make Sense?
There is a 'break-even' point where the monthly fees associated with interchange-plus (usually $10-$30/month) are outweighed by the per-transaction savings. Generally, if your business is processing more than $5,000 per month, or if your average ticket is over $15, interchange-plus will almost certainly save you money.
Conversely, if you are a micro-merchant processing only $1,000 a month with very small tickets (like a coffee shop), the flat-rate model's lack of monthly fees might actually be more economical, despite the higher percentage.
The Hidden Value: Level 2 and Level 3 Data
For B2B companies or those selling to government entities, interchange-plus isn't just an option; it's a necessity. Card brands offer lower interchange rates for corporate and purchasing cards if extra data (like tax amounts or invoice numbers) is sent with the transaction. Flat-rate processors rarely support this, meaning you pay the same high rate regardless of the data you provide. On an interchange-plus plan, properly optimized Level 3 data can drop your costs by 1.00% or more on eligible transactions.
High-Risk Nuance
If your business is in a 'high-risk' category (e.g., nutraceuticals, travel, or gaming), you may find that flat-rate providers like Stripe or PayPal will simply decline your application or freeze your funds without notice. In these instances, a dedicated high-risk merchant account on an interchange-plus model is not only cheaper but provides the stability and underwriting oversight necessary to keep your business alive.
Final Verdict: Strategy over Simplicity
Flat-rate pricing is a starter kit. It is designed to get you up and running quickly. But once your business has consistent volume, that simplicity becomes a liability. To truly maximize your margins, you need the transparency of interchange-plus. It forces your processor to be an honest partner, showing you the raw costs and their specific cut.
At OrbitBNK, we believe that you shouldn't need a PhD in finance to understand your merchant statement. If you're unsure whether you're on the right plan, we're here to help. Upload your most recent merchant statement for a free, no-obligation review. We’ll show you exactly where the hidden markups are and help you transition to a model that actually scales with your success.
Frequently asked questions
Is interchange-plus always cheaper than flat-rate?+
Not always. For businesses processing less than $5,000 monthly, the monthly service fees of an interchange-plus account might outweigh the transaction savings. However, for almost any business above that threshold, interchange-plus is significantly cheaper.
What is a good effective rate for credit card processing?+
A 'good' effective rate depends on your industry and how you take payments. For retail businesses, 1.8% to 2.2% is competitive. For e-commerce, 2.3% to 2.7% is common. If your effective rate is over 3%, you should audit your pricing model immediately.
Does Stripe or Square use interchange-plus?+
By default, no. Stripe and Square primarily use flat-rate pricing. While they offer custom interchange-plus pricing for very high-volume merchants (usually $10M+ in annual volume), most users are stuck with their standard flat fees.
Can I negotiate my interchange-plus markup?+
Yes. Unlike the interchange fees themselves, which are set by the card brands, the 'plus' (the processor's markup) is negotiable. This includes both the percentage markup and the per-transaction fee.
How do I calculate my effective rate from my statement?+
Take the total fees charged for the month and divide them by the total gross sales volume. For example, $250 in fees divided by $10,000 in sales equals a 2.5% effective rate.
See your real processing math
Upload your merchant statement for a free, line-by-line OrbitBNK review.
Start The Clearing