Cafe Merchant Statement Review: Cut Hidden Processing Fees
Perform a cafe merchant statement review to identify fee creep, batch surcharges, and high effective rates eating away at your coffee shop margins.
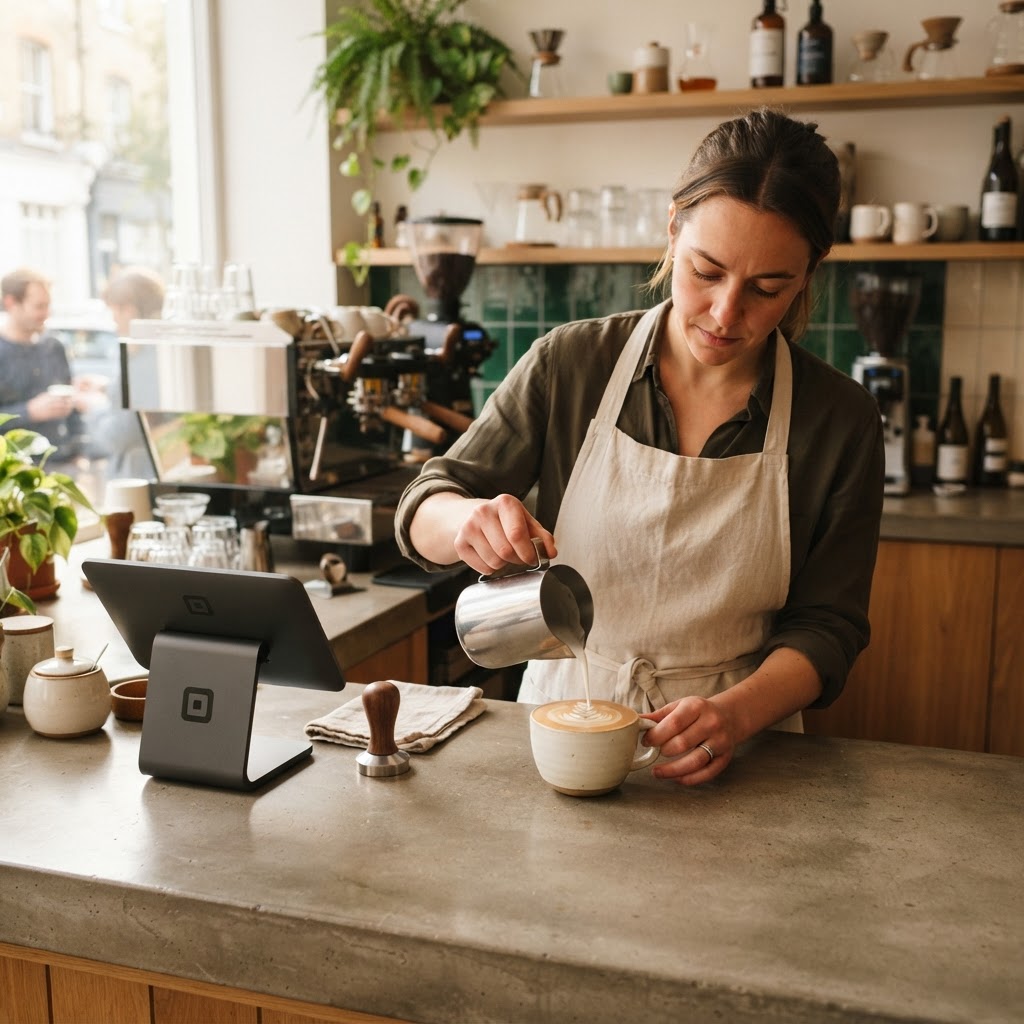
A comprehensive cafe merchant statement review reveals the true processing cost behind high-volume, low-ticket transactions where fixed per-item fees systematically inflate your effective rate above 3.5%. By auditing interchange categories, per-batch settlement fees, non-qualifying surcharges, and terminal rental line items, coffee shop owners can isolate margin erosion and eliminate unearned processor markups.
Running a coffee shop means managing tight unit economics: milk costs rise, roasted beans fluctuate, and labor remains high. Yet credit card processing statements often remain an unread monthly expense. Because typical transactions sit between $4.50 and $9.00, structural pricing traps uniquely penalize cafes and specialty espresso bars.
Why Coffee Shops Pay Disproportionately High Processing Rates
Most retail merchants evaluate payment processing based on headline percentage rates like 2.6% or 2.9%. For coffee shop owners, percentages rarely tell the full story. The real driver of high costs is the per-transaction fixed fee.
Consider a customer buying an iced oat latte for $5.50:
- Processor Plan A: 2.6% + $0.10
- Percentage fee: $0.143
- Fixed fee: $0.10
- Total cost: $0.243 (Effective rate: 4.42%)
- Processor Plan B: 2.9% + $0.30
- Percentage fee: $0.159
- Fixed fee: $0.30
- Total cost: $0.459 (Effective rate: 8.35%)
When a shop processes 400 to 800 transactions a day, a $0.20 difference on per-transaction charges siphons thousands of dollars from gross margin every quarter. High ticket volume at low average order values (AOV) requires pricing structures built around small tickets—such as Visa's Small Merchant or Small Ticket Interchange programs—rather than standard flat-rate plans.
The Anatomy of Fee Creep in Quick-Service Statements
Merchant service statements are deliberately complex, combining hundreds of micro-transactions into bundled line items. When conducting a statement review, check for these four subtle charges common in hospitality and cafe processing:
1. Daily Batch and Settlement Fees
Every time your point-of-sale closes its register shift and transmits the batch to the acquiring bank, a batch fee triggers. Standard pricing is $0.10 to $0.25 per batch. However, processors frequently layer extra costs:
- Separate fees per terminal rather than per merchant account (MID).
- Automated mid-day settlement surcharges when splitting morning and evening shifts.
- "Batch header fees" disguised as standard network transmission costs.
2. Tiered and "Non-Qualified" Downgrades
If your statement displays terms like "Qualified," "Mid-Qualified," and "Non-Qualified," your account is on tiered pricing. In coffee environments, tap-to-pay mobile wallets (Apple Pay, Google Wallet) and rewards cards frequently downgrade to "Non-Qualified" tiers. You might expect to pay 1.7%, but the transaction clears at 3.65% plus penalty surcharges simply because the customer used an airline points card for their morning drip coffee.
3. Ancillary Software and Equipment Rentals
Many POS providers lock counter-service businesses into expensive hardware rental programs. Paying $49 to $99 a month for an iPad stand, card reader, and receipt printer over a multi-year term means paying triple the device's retail value. Look for line items such as "POS SaaS Fee," "Gateway Support," "PCI Non-Validation Fee," and "Regulatory Compliance Surcharge."
4. Statement and Account Maintenance Charges
Legitimate card network assessments (Visa, Mastercard, Discover, Amex) are mandatory, but "statement delivery fees," "customer service fees," and arbitrary monthly minimums are discretionary processor markups that provide zero functional value to your floor operations.
How to Calculate Your Cafe's Real Effective Rate
Headline pricing is marketing; effective rate is accounting reality. Calculating your real processing cost requires a simple formula using your end-of-month processing statement:
$$ ext{Effective Rate} = \left( \frac{ ext{Total Processing Fees Charged}}{ ext{Total Gross Card Volume}} \right) imes 100$$
For example:
- Gross Monthly Sales: $42,500
- Total Fees Deducted: $1,572.50
- Calculation: ($1,572.50 / $42,500) * 100 = 3.70% Effective Rate
For a standard counter-service cafe with card-present transactions above 85%, an effective rate exceeding 2.7% to 3.1% indicates unoptimized pricing, inappropriate pricing models (flat-rate vs. interchange-plus), or excess non-interchange fees.
Why Coffee Shops Face Holds, Reserves, and Underwriting Triggers
Coffee shops are typically viewed as low-risk retail businesses by acquiring banks. However, operational shifts can quietly trigger automated risk algorithms, resulting in frozen funds or rolling reserves:
- Sudden Spike in Average Order Value: If your average ticket is $7.50, and you run a $4,500 espresso machine sale, catering invoice, or corporate gift-card balance through your standard counter terminal, the automated risk engine may flag it as fraudulent or unauthorized.
- High-Speed Chargebacks on Gift Cards: Fraudsters sometimes test stolen card batches on cafe online order pages or physical contactless readers using automated gift card balance purchases.
- Seasonal Volume Surges: A summer patio cafe or tourist-hub coffee shop tripling its volume from May to July can trigger velocity limits if processing caps were not updated with the underwriter during spring.
If your funds are held, providing proof of delivery, catering agreements, and inventory receipts is required to unfreeze cash reserves. Understanding how acquiring banks categorize merchant risk across diverse food and retail models helps prevent these operational stalls; see our breakdown across different processing industries.
When to Switch Processors (and When to Renegotiate)
Not every statement problem requires ripping out your terminals and changing your hardware setup. Here is how to decide whether to renegotiate or migrate:
When to Renegotiate
- You are on Interchange-Plus pricing: If your processor already passes through true interchange rates and only adds a distinct markup (e.g., Interchange + 0.25% + $0.08), you can negotiate that specific basis-point markup and per-transaction fee based on your trailing 12-month volume.
- You are paying PCI compliance non-validation fees: These $20 to $50 monthly penalties disappear as soon as you complete the annual self-assessment questionnaire (SAQ).
When to Switch Processors
- Locked into Flat-Rate Pricing on High Volume: Once your cafe processes more than $15,000 monthly, flat-rate pricing models (such as 2.6% + $0.15) become noticeably more expensive than genuine interchange-plus arrangements.
- Proprietary Hardware Lock-In with Auto-Renewals: If your processing provider unilaterally raises transaction fees while restricting POS functionality to their proprietary gateway, evaluating alternative options becomes a balance-sheet necessity.
- Repeated Unexplained Fund Holds: If simple catering invoices trigger 14-day settlement holds, your processor’s underwriting model does not fit your operational profile.
What Documents You Need to Switch or Re-Underwrite
When transitioning to a competitive payment processor or seeking customized underwriting terms, prepare an organized file to avoid delays:
- 3 consecutive months of complete merchant processing statements.
- 3 months of business bank statements confirming processing deposits.
- Voided business check or signed bank verification letter.
- Government-issued photo ID of the majority business owner(s).
- Business formation documents (Articles of Organization, EIN confirmation letter).
- Proof of menu pricing and an explanation of catering/high-ticket offerings (to establish appropriate single-ticket velocity limits).
How OrbitBNK Helps
Navigating merchant processing contracts, decoding complex interchange tables, and managing merchant account underwriting requires specialized intelligence. OrbitBNK provides clarity without the sales rhetoric:
- Granular Statement Audits: OrbitBNK analyzes your line items to uncover interchange downgrades, hidden processor margins, and inflated per-transaction fees specific to counter-service and food-and-beverage profiles.
- Underwriting File Preparation: We help compile underwriting packages with realistic ticket limits, safeguarding high-volume and catering transactions from risk freezes and unexpected reserves.
- Processor Matching: OrbitBNK evaluates your POS setup, average ticket size, and monthly volume to identify suitable payment processors offering competitive terms tailored to your business model.
Take Control of Your Margins
Credit card processing fees should not erode the hard-earned profit on every cup you pour. Every fraction of a percent saved directly supports your bottom line, equipment investments, and staff retention.
Upload your latest processing statement for a free statement review and see how your current effective rate compares against true interchange costs.
Frequently asked questions
What is a good effective rate for a coffee shop?+
For most quick-service coffee shops with predominantly in-person (card-present) transactions, a healthy effective rate generally falls between 2.3% and 2.9%. If your effective rate climbs above 3.3%, you are likely dealing with high fixed per-transaction fees, tiered pricing downgrades, or extra non-interchange account fees.
Why does a flat-rate processing plan hurt low-ticket cafes?+
Flat-rate processing structures typically combine a percentage with a fixed fee, such as 2.6% + $0.10. On a $4.00 espresso drink, that $0.10 fixed fee alone represents 2.5% of the total purchase, driving your actual fee on that single transaction to over 5.1%.
Can I negotiate my coffee shop's processing rates?+
Yes. While you cannot negotiate the interchange rates charged by card brands like Visa and Mastercard, you can negotiate the processor's markup on an interchange-plus plan, along with per-batch settlement fees, statement charges, and terminal rental rates.
Why did my processor freeze funds from a catering order?+
Acquiring banks use automated risk filters based on your historic average ticket size. If your cafe typically runs $6.00 tickets and suddenly processes a $3,500 catering or equipment sale, the processor's automated system may freeze the payout pending verification of fulfillment and customer identity.
See your real processing math
Upload your merchant statement for a free, line-by-line OrbitBNK review.
Start The Clearing

